Aegon: Transformation Prices To Think about, However Lengthy-Time period Potential (NYSE:AEG)

Poulssen
On the Lab, we have an extended historical past of Aegon (NYSE:AEG), however we should always remind our new readers that this firm gives life insurance coverage, asset administration actions, and pension options. Aegon was funded in 1880 in The Hague (Netherlands) and served extra than ten international locations, with vital operations within the UK and the US. Certainly, our funding fairness story was backed by 1) the Transamerica division’s upside, 2) a supportive Shareholders’ Remuneration, and three) a sound administration staff with clear de-risking methods ongoing. Intimately, Aegon has undergone a restructuring underneath its present administration staff with the sale of Aegon Netherlands. This has quickly improved the corporate’s ROE and its profitability within the US life enterprise.
After a tumultuous begin in August, markets have entered a quiet interval. Within the meantime, authorities bond yields have moved sharply in a brief area of time. The vital near-term occasion is Jackson Gap, with expectations across the US Federal Reserve chopping cycle starting in September. With a inventory worth efficiency of minus 8% since August began and the corporate’s H1 numbers launched, this is a wonderful time to evaluate Aegon’s financials and expectations.
H1 Outcomes
Within the semester, the corporate reported an IFRS working earnings of €750 million (Fig 1) and a web lack of €65 million. Nonetheless, the online outcomes had been considerably impacted by minus €312 million of unfavorable honest worth objects and minus €403 million expenses as a consequence of modifications in mortality assumption. Excluding these unfavorable one-time objects, the consequence was virtually aligned with Wall Road consensus estimates. That stated, Aegon’s working outcomes had been 8% decrease vs. H1 2023. Consequently, the corporate shareholders’ fairness decreased to minus 6%. This efficiency was supported by a optimistic evolution of the CSM launch.
On the solvency ratio, the US RBC ratio was 9 foundation factors higher than the consensus at 446% (Fig 2). This was supported by a optimistic credit score expertise as a consequence of higher-for-longer charges and favorable fairness markets. On the group degree, the solvency ratio reached a rise of virtually 189% because of the corporate’s capital era.
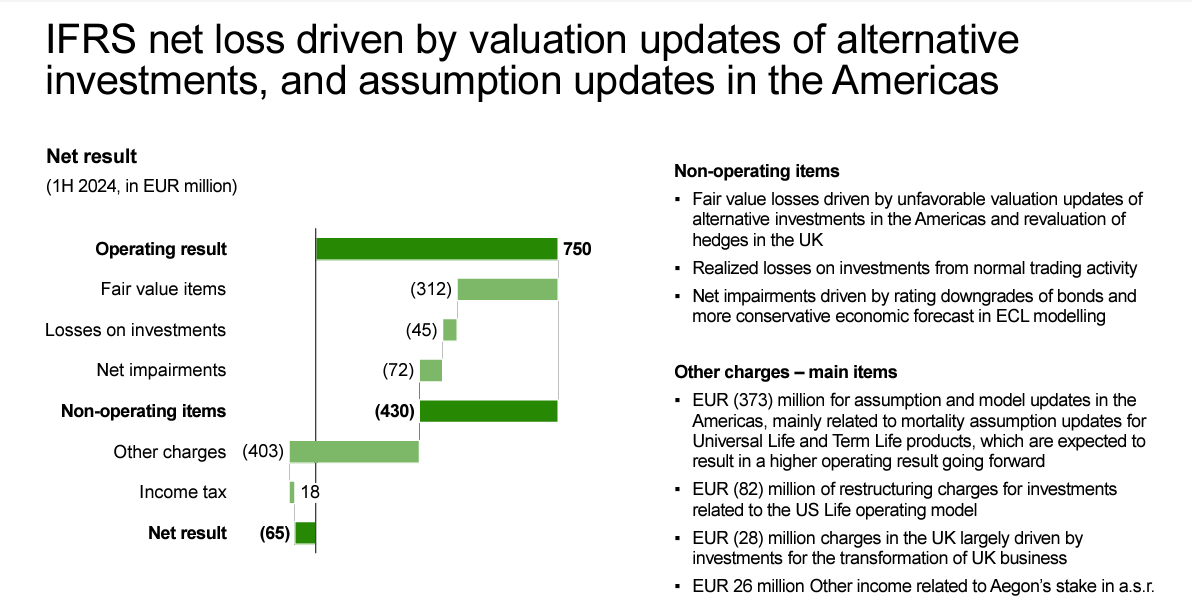
Aegon outcomes
Supply: Aegon Q2 outcomes presentation – Fig 1
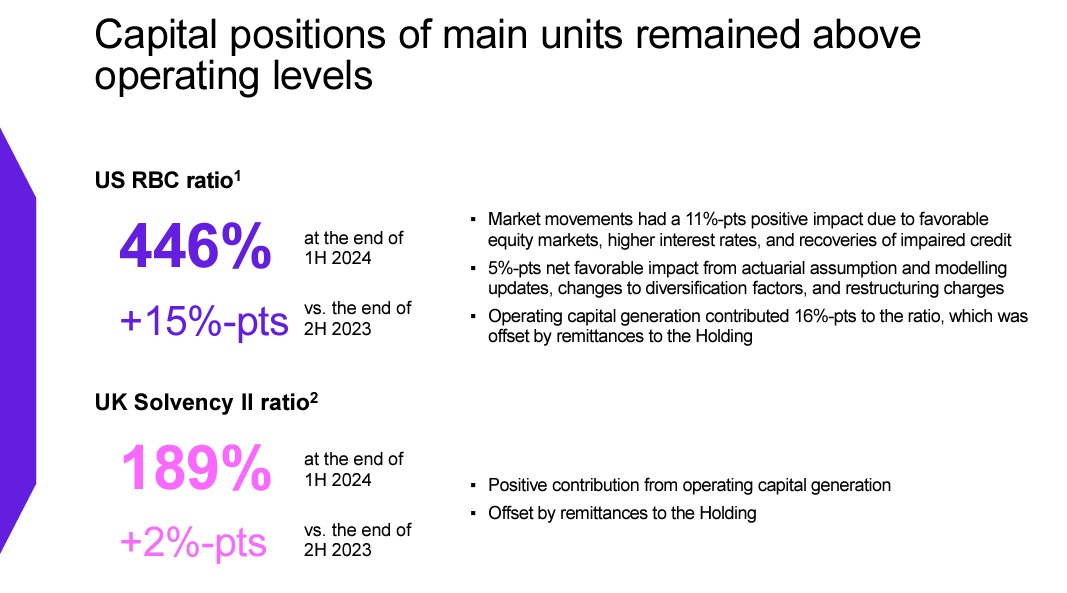
Aegon Solvency Ratio Evolution
Fig 2
UK Strategic Plan and our Optimistic Takes
(Wanting forward, we mission a juicy capital return). Final time, we reported a optimistic evolution in Aegon’s tasty shareholders’ remuneration. As a reminder, following the completion of the €1.5 billion share repurchase plan, Aegon initiated a brand new buyback of €200 million. The interim dividend was additionally elevated to €0.16 and was aligned with our expectations. That stated, right here on the Lab, we anticipate a minimal €300 million share buyback from 2025, which can be lined by HoldCo money stream. In our view, with the present dividend yield projection in 2025, Aegon nonetheless gives a lovely capital return of not less than 10%.
(Unlocking property worth). The corporate launched a brand new strategic plan on the finish of June. Having fastidiously analyzed the UK enterprise replace, we consider the corporate has proven a transparent technique to enhance Aegon’s Office and Advisor platforms and their web flows. Nonetheless, the excessive upfront transformation prices will doubtless not drive optimistic elementary earnings modifications within the upcoming years. Our division’s decreased earnings modifications replicate decrease working revenue over 2024 and 2025 as a consequence of a £70/80 million restructuring cost per 12 months. That stated, with the working prices being absorbed by the UK enterprise, the Group’s operational capital era will barely improve with increased holding money stream in our forecast numbers. Even when we’re not anticipating this state of affairs, we consider the market would react favorably if the CEO ever determined to get rid of the UK life enterprise. Aegon focuses on constructing Transamerica’s new earnings capabilities to unlock shareholders’ worth. This pattern has been optimistic. Our staff believes that ASR share gross sales is perhaps the subsequent optimistic catalyst, however the long-term ambition is a US IPO for the Transamerica division. On this regard, the highest administration staff has an distinctive observe document.
(Noteworthy ongoing outcomes). In keeping with Transamerica’s efficiency in H1, distribution and safety segments are rising strongly, with productiveness enhancements and elevated market demand for the corporate’s merchandise (Fig 3). Our staff believes Aegon is on observe to realize the operational KPI goal on this section. As well as, in comparison with the previous, Transamerica’s RBC ratio sensitivity to rates of interest and equities has considerably decreased lately (Fig 4). This gives draw back safety that can’t go unnoticed. Supportive new enterprise pressure and unfavorable experiences in Monetary Property variances have impacted the efficiency. Nonetheless, the corporate’s steerage of €1.1 billion stays unchanged.
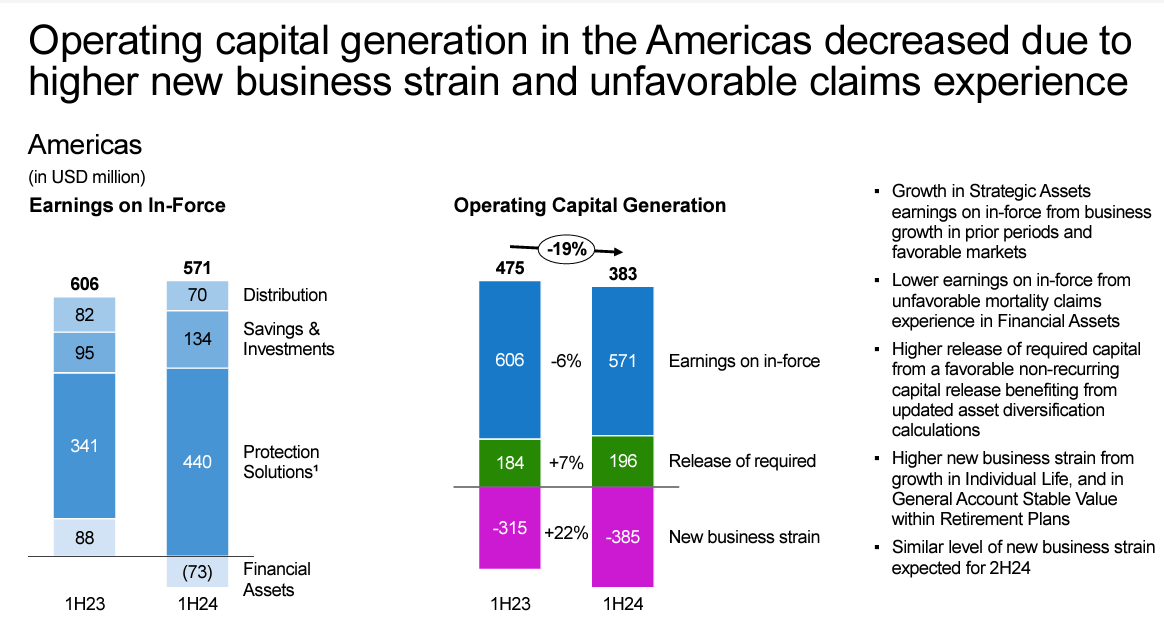
Transamerica efficiency
Fig 3
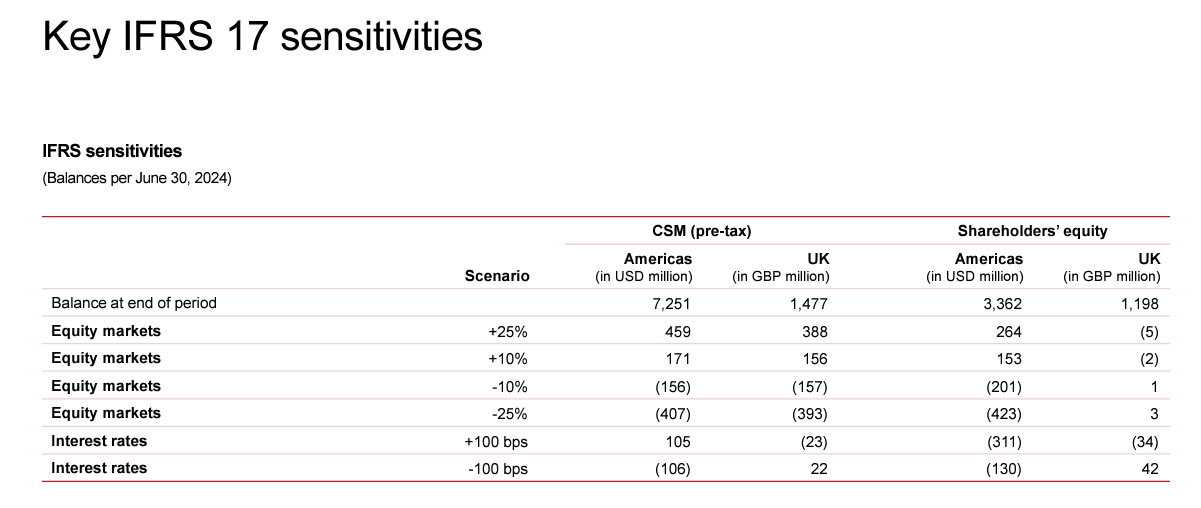
Aegon Sensitivity
Fig 4
Adjusting Estimates and Valuation
Q2 earnings weren’t a comparatively quiet quarter for the corporate. Right here on the Lab, we barely decreased our estimates to replicate Aegon’s UK Technique Replace. That stated, we reiterate our obese ranking given the corporate’s engaging group capital return outlook and upside from potential disposal. As well as, we don’t anticipate vital capital ratio loss from markets regardless of the implied volatility. With the corporate’s steerage unchanged and an H1 working capital era of €588 million, we had been above the corporate’s outlook. In our earlier protection, we had been forecasting a pre-tax operational earnings of €1.6 billion. This additionally included the a.s.r. dividend cost, which was totally paid within the quarter. With increased funding and transformation prices within the enterprise, we determined to decrease our operational earnings by €150 million. As well as, we estimate a decrease Group Solvency ratio by 5 foundation factors. Together with the optimistic accretion from buybacks with decrease share counts, we decrease our adjusted 2024 EPS estimates from €0.79 to €0.74.
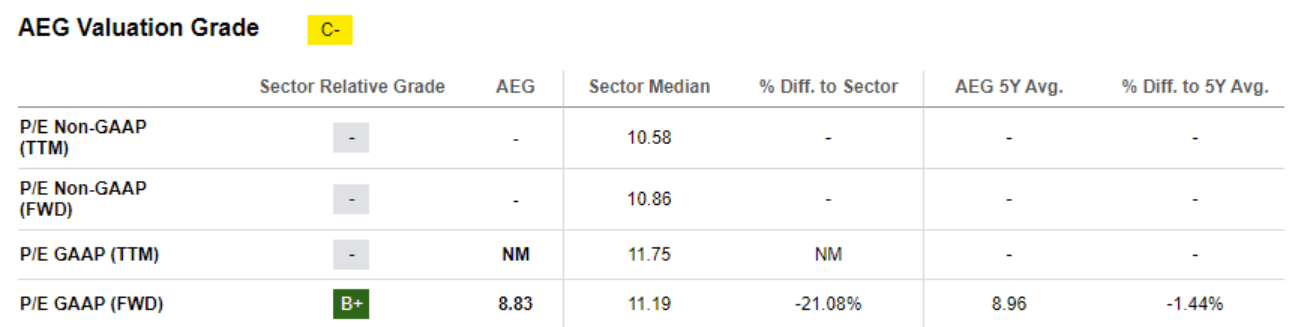
Concerning the valuation, we worth it the identical approach as the remainder of the sector and closest friends, equivalent to NN Group. Persevering with to use an 8x P/E goal (Fig 5), we arrive at a worth of €5.92 per share. As a reminder, this 20% low cost is aligned with Aegon’s previous valuation and the MSCI Europe Insurance coverage Index, which trades at a P/E ahead a number of set at 10.3x.
Aegon SA Information Valuation
Fig 5
Dangers
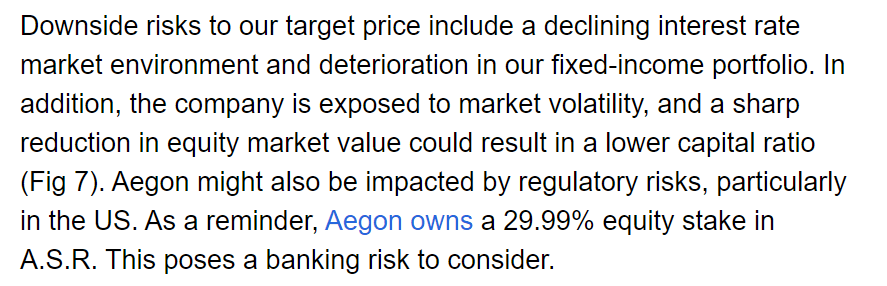
Our staff has 4 years of protection of Aegon. The principle dangers are included within the part under (Fig 6). As well as, we report: 1) execution dangers on new enterprise actions within the Transamerica division in addition to increased restructuring expenses within the UK division, 2) decrease earnings projection as a consequence of unfavorable mortality claims, 3) increased launch of capital from regulatory necessities or new enterprise pressure, and 4) decrease buyback evolution. With Aegon’s worldwide growth and significant US and UK actions, the corporate is perhaps impacted by FX modifications.
Mare Ev. Lab Earlier Dangers Part
Fig 6
Conclusion
Regardless of the Q2 unfavorable one-off, new enterprise development is supporting Aegon’s earnings progress. Forward, we see draw back safety from the corporate’s present asset base — associated to disposal optionality. As well as, we see assist from strong working capital era, which continues to supply a lovely capital remuneration coverage. Our purchase ranking is then confirmed.
Editor’s Be aware: This text discusses a number of securities that don’t commerce on a significant U.S. trade. Please pay attention to the dangers related to these shares.