ByteTree Analysis Q3 2026 Quarterly Investor Letter
filo/iStock by way of Getty Photographs
Since 2016, our mission has been to assist individuals make investments extra successfully. We do that by delivering actionable, high-quality funding steering at an inexpensive worth. With all the knowledge on the market, we assist traders by distilling our recommendation into mannequin portfolios, explaining each new funding suggestion in actual time.
On this Q3 2026 replace, I shall overview our flagship product, The Multi-Asset Investor. You might as an alternative choose to look at our Q3 overview webinar, which fits into extra element.
Letter from Charlie Morris, CEO
Bond yields have change into crucial macroeconomic theme. After the surge in 2022, the stabilisation is over, and new highs have been seen throughout the developed world. The standout exception has been China, the place the housing stoop has led to a interval of debt deflation.
International 10-Yr Bond Yields
Supply: Bloomberg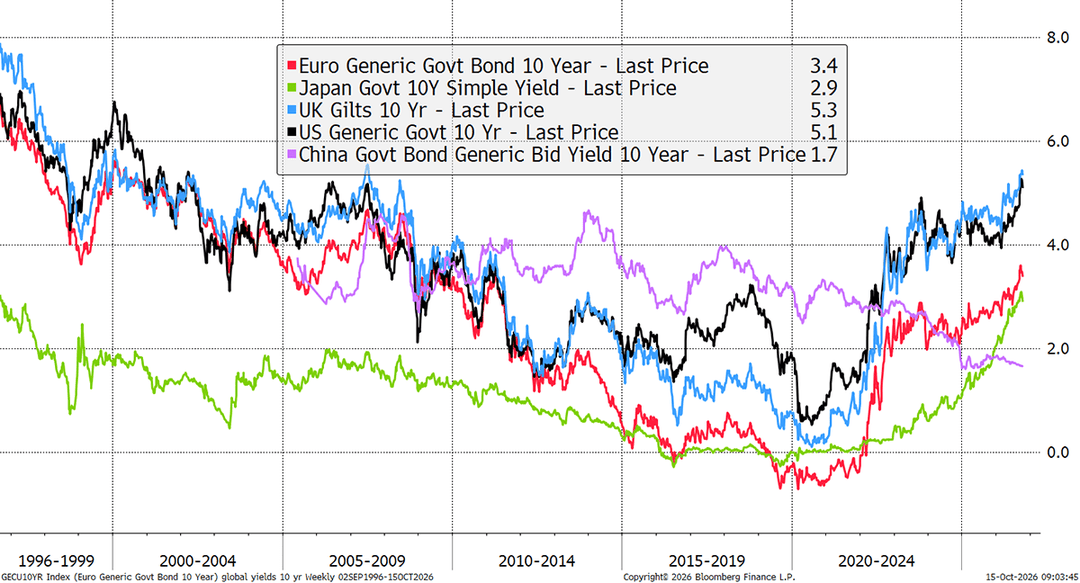
Some imagine the rising yield displays normalisation, as economies recuperate from the post-2008 period and the deflationary interval of zero rates of interest. Development and inflation, particularly within the US, have picked up, and yields mirror that. Others suppose this pertains to creditworthiness, as ballooning deficits imply extra bond issuance towards tight budgets.
It’s almost certainly normalisation at first, however since most economies can not afford larger charges because the curiosity invoice retains on rising, it is going to find yourself morphing right into a sovereign debt disaster. Governments ought to be radically chopping again spending earlier than they’re pressured to take action by the markets. Some perceive that; others don’t.
In current points, I’ve written about how larger yields have an effect on market breadth and about “modified period”, which measures bond threat. In 2020, gilts paid round 1%, at a time when a 1% transfer within the 10-year yield would result in a 13% revenue or loss on the capital. At this time, they pay 5.5%, with a modified period of seven%. In different phrases, a 12 months’s earnings can virtually stand up to a 1% transfer in yields. This doesn’t make bonds a powerful purchase, nevertheless it definitely makes them much less dangerous.
Gilt Index: Modified Length
Supply: Bloomberg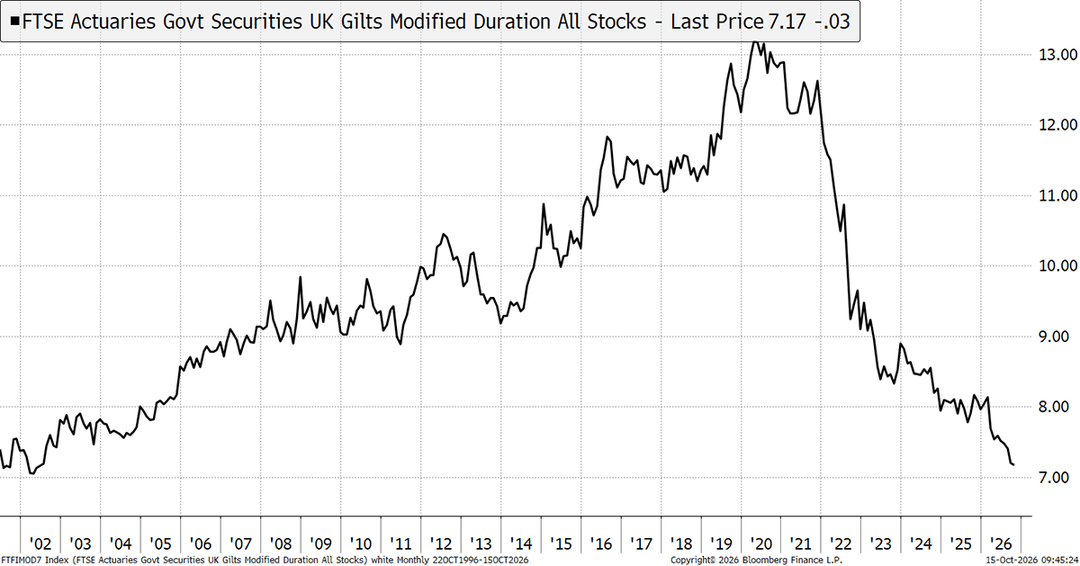
The breadth story is much more seismic. Rising yields make low-growth, or no-growth, shares look unhealthy as bonds pay extra engaging yields. That costs development at a premium, and since development shares are few in comparison with regular shares, the market breadth has deteriorated. Meaning fewer shares have been beating the market (blue), whereas many are lagging (purple).
International Fairness Alpha Breadth is Weak
Supply: Bloomberg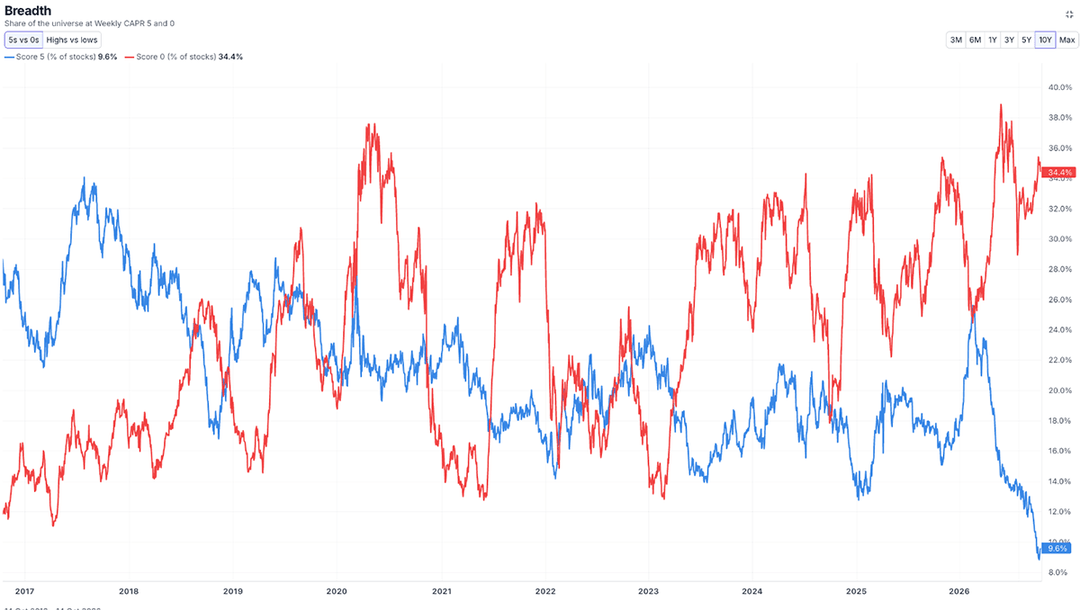
Our analysis means that this can be a file low going again many years, with related readings not seen for the reason that late Nineties. That was additionally a interval of rising yields, which favoured development shares, whereas worth was shunned.
To maintain the market wanting sturdy with low breadth, it follows that the massive shares are performing higher than the smaller shares. Development shares additionally are typically extra risky than different shares, which can be much less thrilling however supply larger certainty. It seems that to beat the market, one of the best technique is to embrace ultra-large and risky shares. Make sure, these should not regular instances.
International Shares Dimension and Volatility
Supply: ByteTrend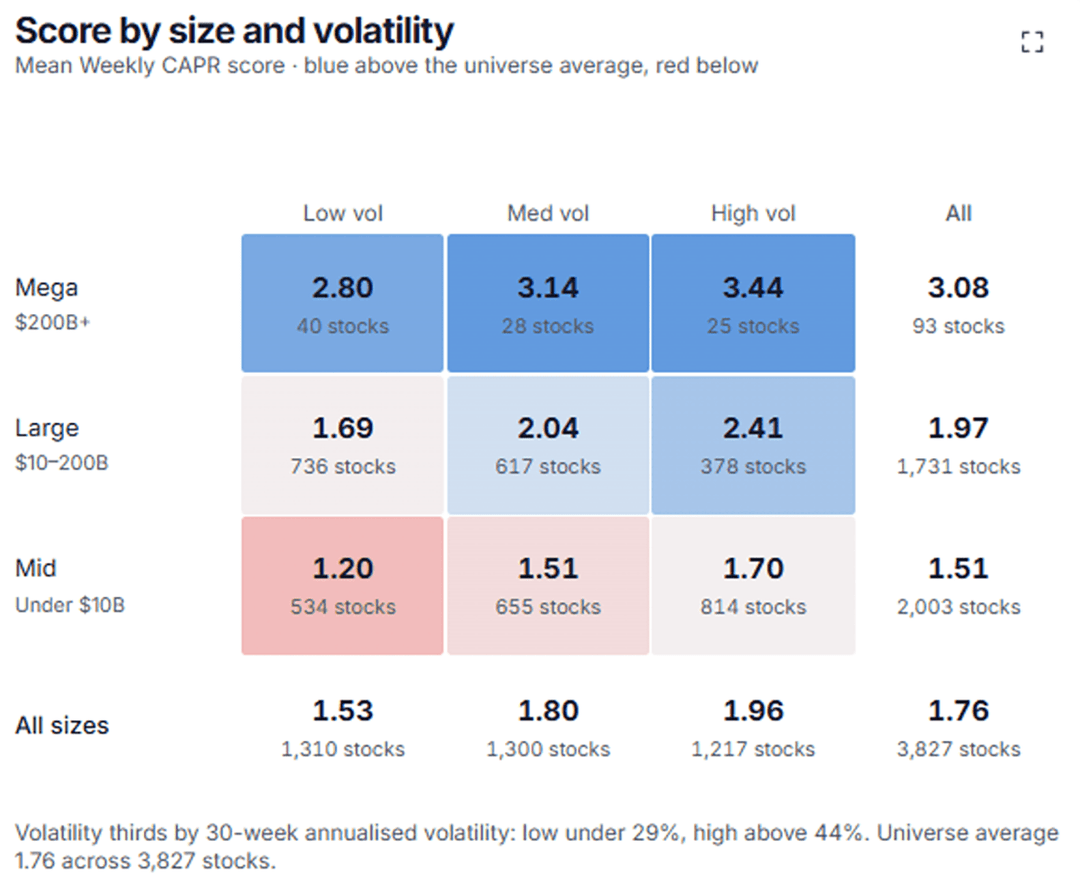
In distinction, calm small shares are underperforming considerably and can supply a great alternative when the tide turns. As soon as once more, it jogs my memory of the late Nineties. The massive, high-volatility shares did nicely till they didn’t. After March 2000, the much less risky shares and smaller caps led the marketplace for the following six years.
Excessive Beta vs Low Volatility post-Dotcom Growth
Supply: Bloomberg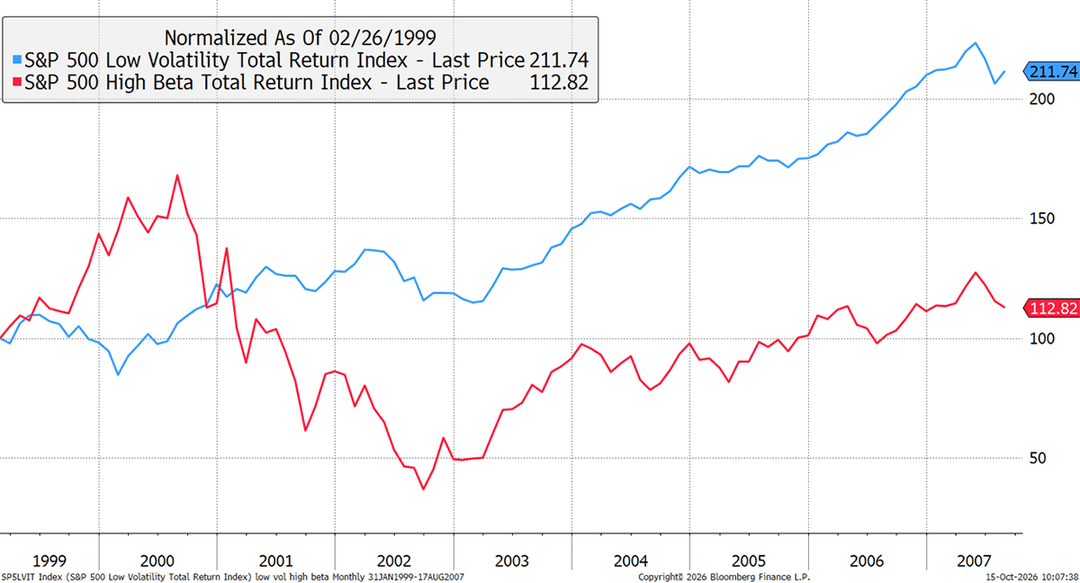
After all, the backdrop to all this focus and large-cap outperformance could be very excessive valuations for the market. The Shiller P/E Ratio exhibits the value of shares towards their common earnings over the past ten years. The height in 1929 was round 31x, the height in 1999 was 45x, and at present we’re at 41x. Throughout crashes, it has gone as little as 5x. Not solely that, however margin debt is close to traditionally excessive ranges, suggesting traders are leveraged into this concentrated and overvalued market. This type of state of affairs makes the entire thing fragile.
Shiller P/E Ratio
Supply: Multpl.com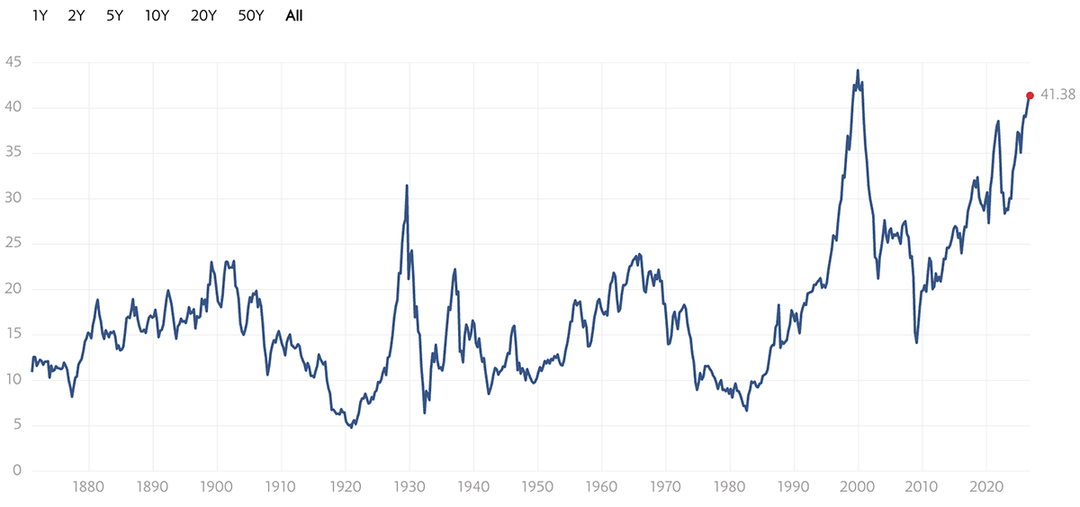
In the previous few days, the AI commerce has weakened as soon as once more. They pulled again initially in July, however didn’t crash. Now, they’re falling once more. There have been many false begins on the finish of this bull market, which makes the bears nervous to assert the highest is in for concern of being flawed once more. For now, when tech weakens, capital flows again into the remainder of the market: a rotation. Hassle will come when different sectors observe it decrease in unison.
Semiconductor Inventory Costs
Supply: Bloomberg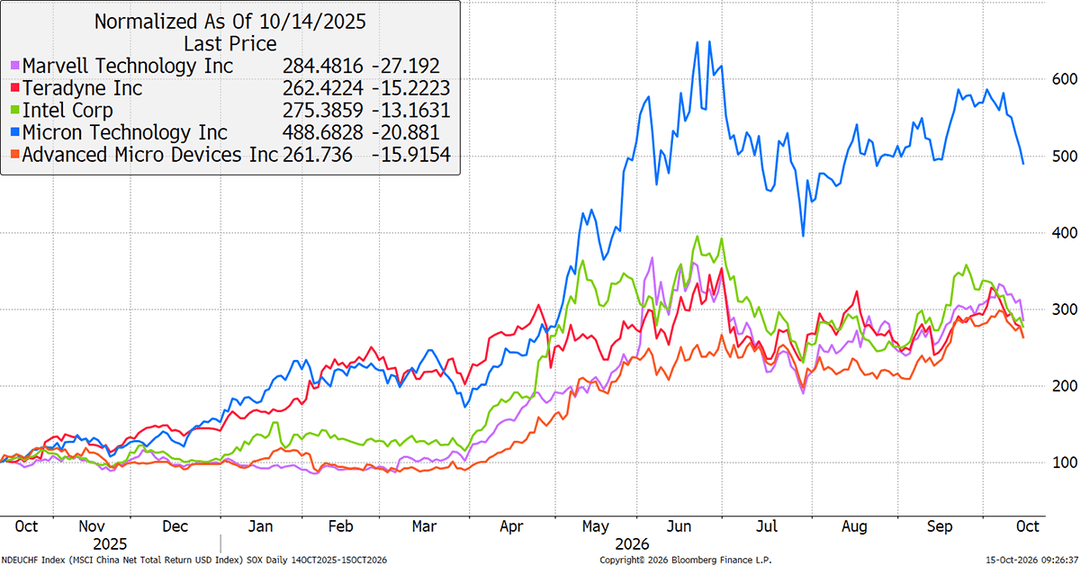
It has additionally been an fascinating interval in commodities. Oil has completed nicely this 12 months, adopted by copper. Gold and silver have been all the fashion till January however have cooled since. Copper stays in excessive demand because the world electrifies, whereas agriculture has remained comfortable. That is regardless of the climate results from El Niño and the surge in fertiliser costs.
Commodities Combined however Constructive
Supply: Bloomberg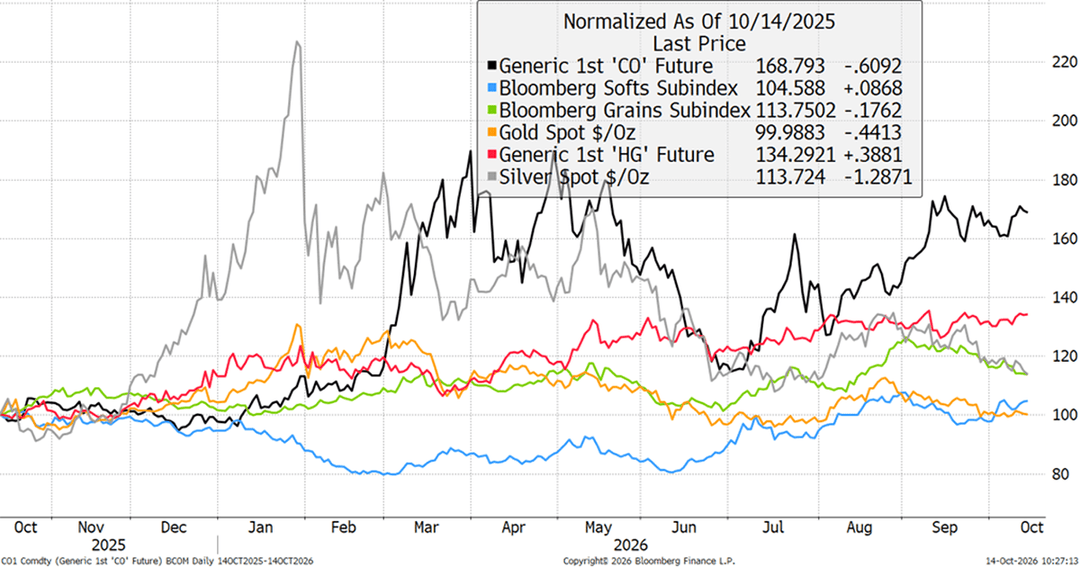
The Multi-Asset Investor
The Multi-Asset Investor is a commentary and two portfolios, Whisky and Soda, that cowl conventional belongings. The portfolios are designed to be simple to duplicate for traders managing their very own cash. Soda is low turnover and medium threat. Whisky is extra dynamic and medium-high threat. It’s written by Charlie Morris and up to date weekly, with further Flash Notes when quick motion is required.
The Whisky Portfolio
Whisky had a great quarter, boosting returns to 13.6% in 2026, which is 3.7% forward of its benchmark, the FTSE 100. The portfolio was sitting fairly in January, on the gold peak, and regardless of a number of reductions in publicity, efficiency cooled thereafter. Volatility adopted within the second quarter, however this final quarter has been a calmer journey.
Whisky vs FTSE 100
Supply: Bloomberg, ByteTree. Complete Return in GBP from 29 January 2016 to 29 September 2026.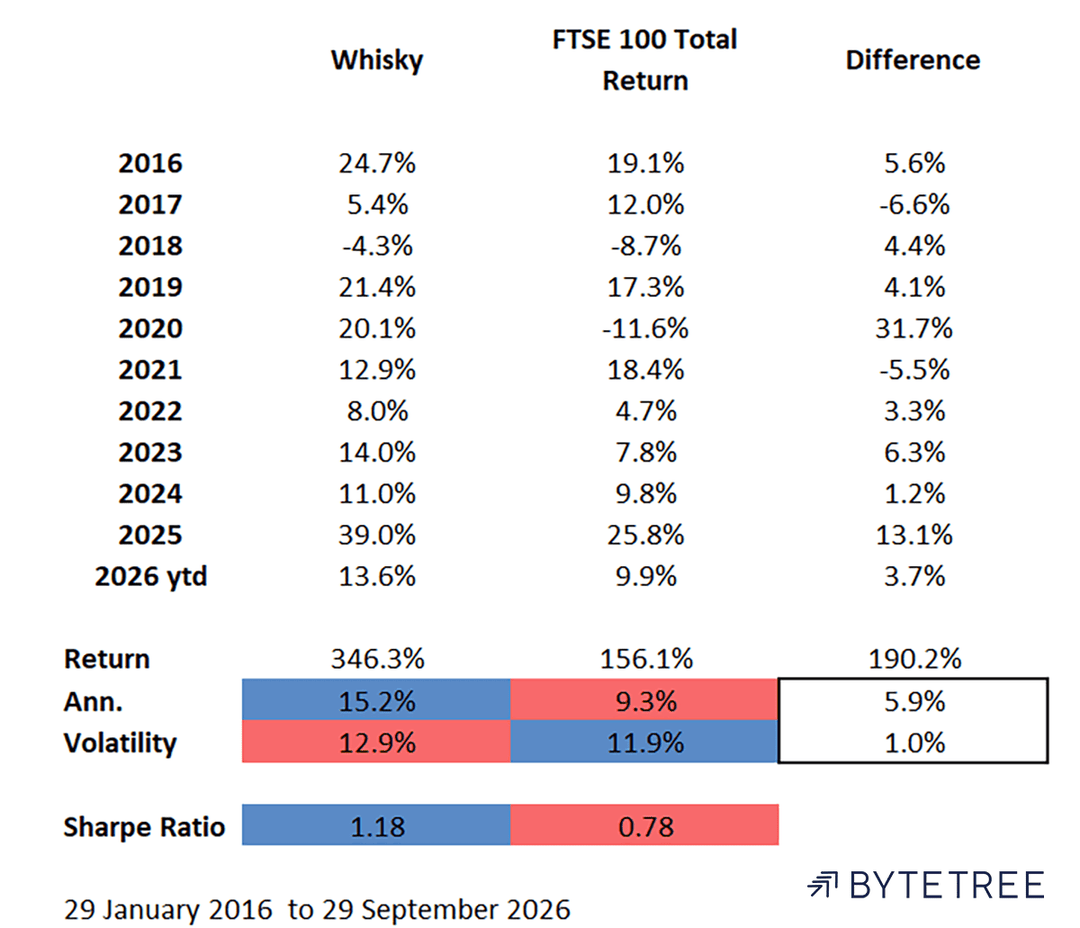
The long-term returns have been very passable. The perfect years have been 2020 and final 12 months. 2020 benefited from early promoting adopted by pouncing on the restoration commerce. Final 12 months was buoyed by treasured metals. This 12 months has been lumpier, with a cornerstone in high quality shares and extra tactical positions in worth and momentum alternatives, in addition to treasured metals, a modest place in Bitcoin, and different commodities, primarily vitality.
Whisky Portfolio Efficiency
Supply: Bloomberg, ByteTree. Complete Return in GBP from 29 January 2016 to 29 September 2026.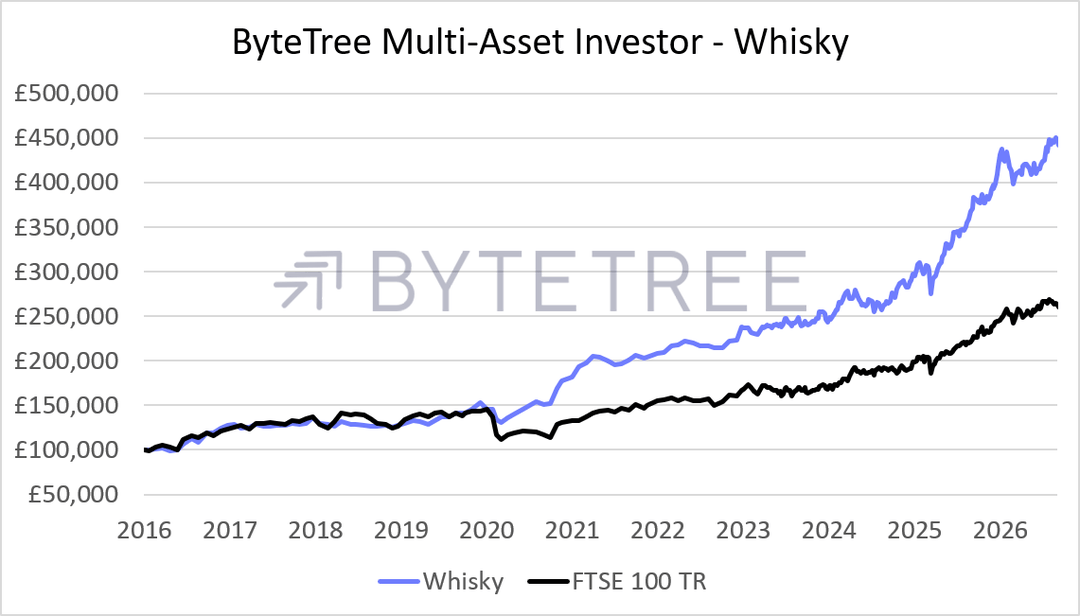
The Soda Portfolio
In distinction to its sturdy lead to 2025, Soda has lagged this 12 months. It holds extra conservative belongings, reminiscent of balanced funds, worth, high quality and gold. It’s 3.9% behind the balanced index in 2026. The index is closely skewed towards US equities, which explains the outperformance. Figuring out that giant tech is a significant bubble that would blow at any time, I’ve prevented it. Since 2022, Soda’s relative efficiency has been pushed by that concept. When US tech surged, Soda lagged the market and vice versa.
Soda vs FTSE Non-public Balanced Index
Supply: Bloomberg, ByteTree. Complete Return in GBP from 29 January 2016 to 29 September 2026.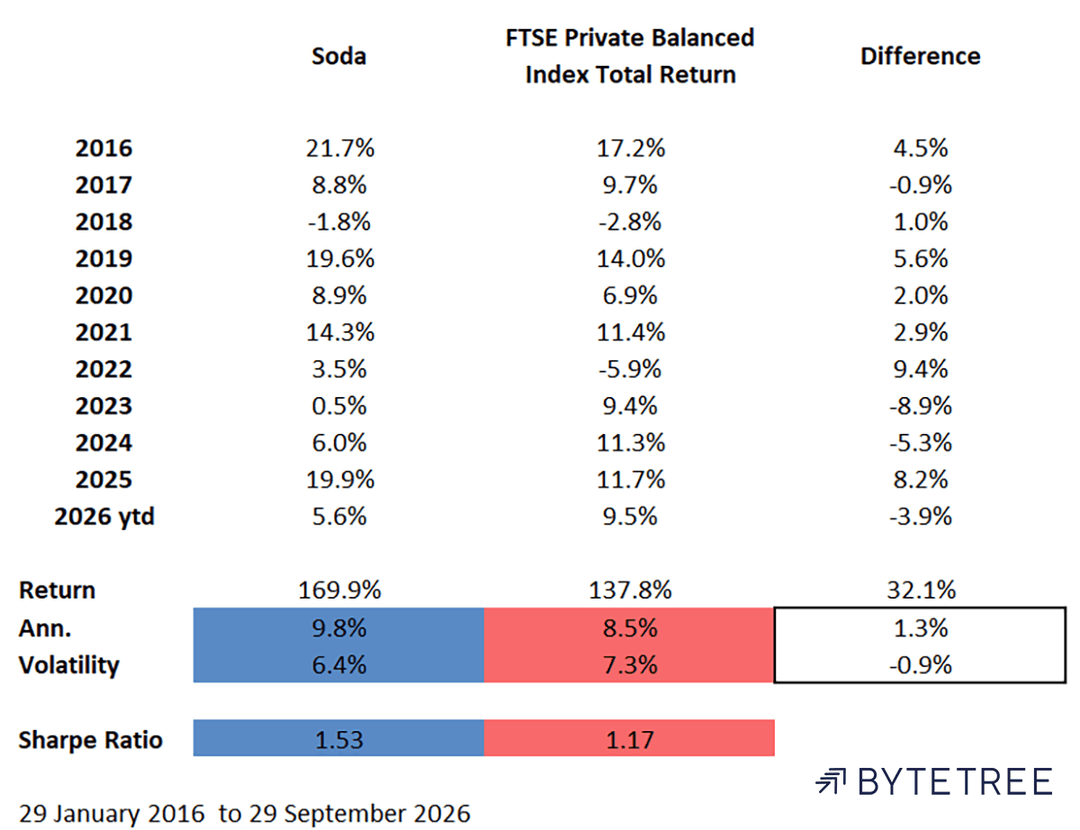
In Soda, my precedence has at all times been, and at all times will likely be, capital preservation over capital positive factors, as proven by the persistently decrease portfolio volatility. That tends to repay probably the most when markets come beneath strain and fare worse. Growing threat, when it’s least dangerous to take action, has resulted in engaging risk-adjusted returns.
Soda Portfolio Efficiency
Supply: Bloomberg, ByteTree. Complete Return in GBP from 29 January 2016 to 29 September 2026.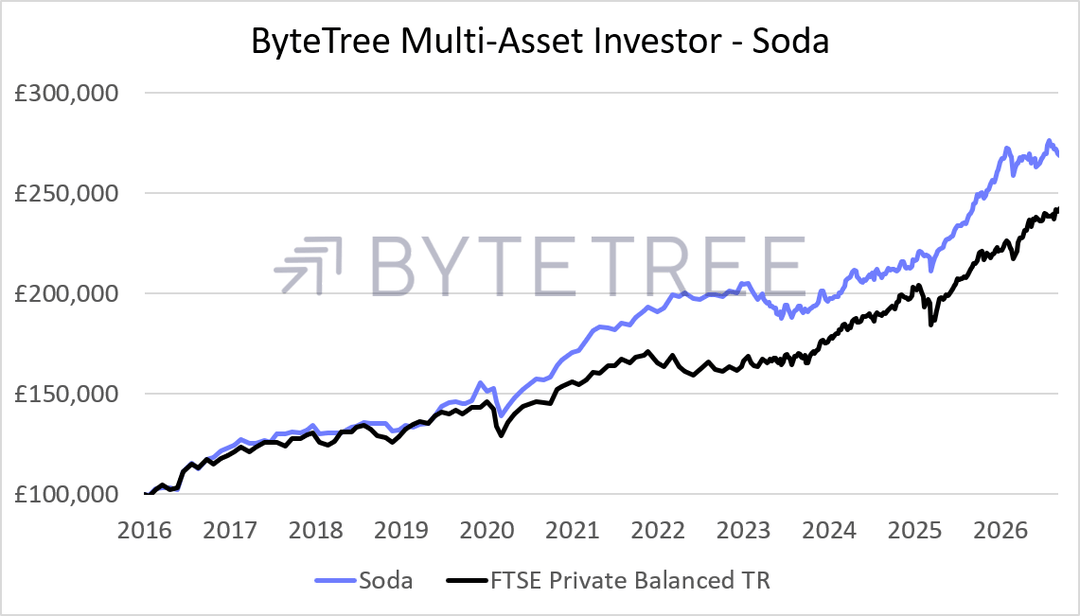
Lengthy-term, we stay forward of the market, nevertheless it has been difficult to widen that hole additional in an atmosphere the place giant tech has been the main commerce. When the breadth reverses, alternatives will likely be in abundance. I will likely be oversold sectors reminiscent of property and the buyer, rising market international locations and small-caps. In that sense, good instances lie forward.
Outlook
Markets are excessive in some ways, as proven in equities, bonds and commodities. We’ve got an vitality shock mixed with a bond shock, and a complacent stockmarket that assumes AI will plaster over the cracks. I imagine change is coming, and traders who keep on with diversification and sound monetary evaluation will climate the storm.
Editor’s Word: The abstract bullets for this text have been chosen by Looking for Alpha editors.